The CPCA released passenger vehicle market data for the first week of September 2026. From September 1 to 6, nationwide passenger vehicle retail sales were 210,000 units, down 19% year on year and down 1% month on month; manufacturer wholesale sales were 207,000 units, down 21% year on year and up 13% month on month. New energy vehicles performed relatively steadily, with retail sales of 150,000 units, down 3% year on year, and wholesale sales of 156,000 units, up 2% year on year; retail penetration was 71.5%, and wholesale penetration was 75.1%. Wholesale sales of fuel vehicles fell 53% year on year, dragging down the overall market. The CPCA believes customer traffic during the golden September and silver October period may recover, but the high base may limit the extent of the rebound.
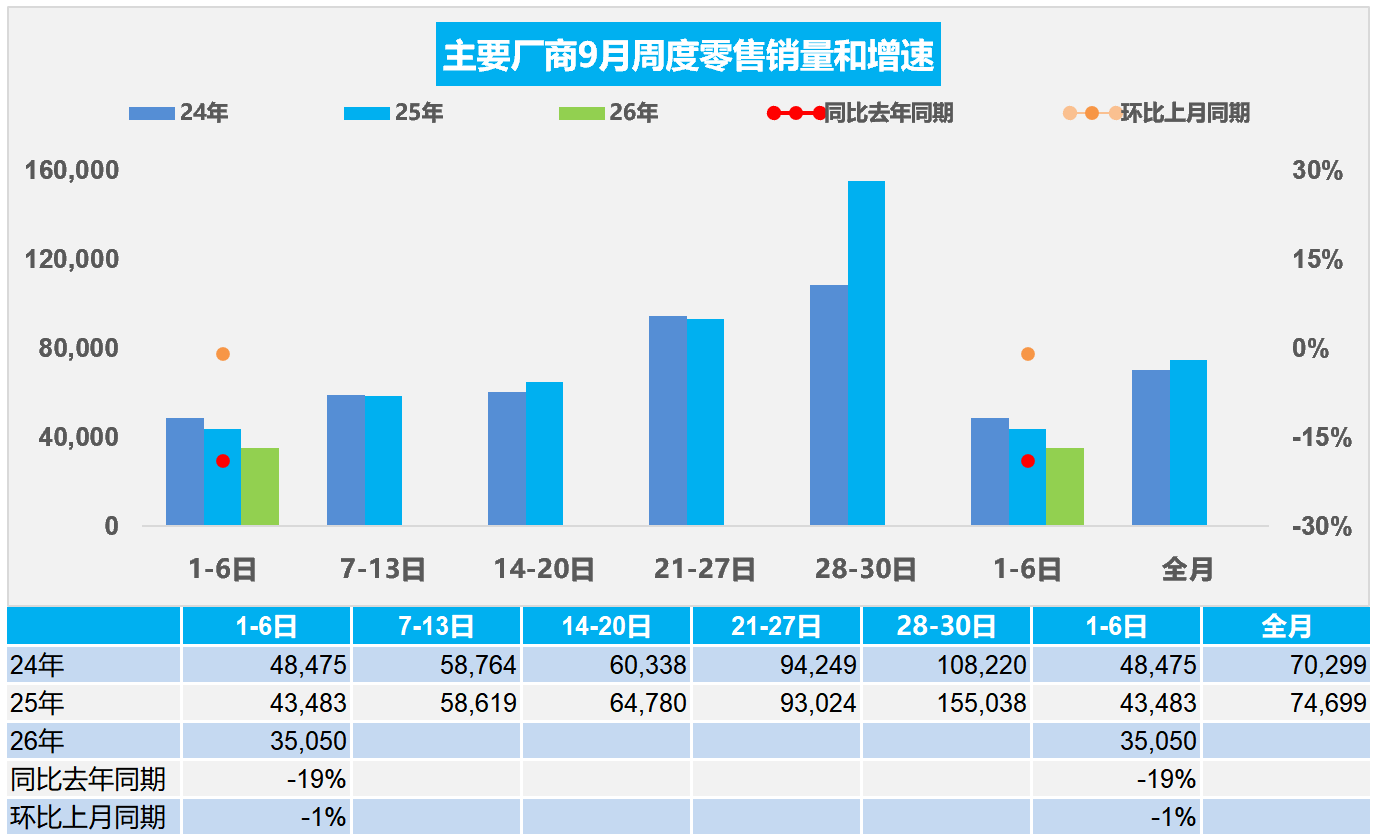
On September 10, the China Passenger Car Association (CPCA) released scan data on the passenger vehicle market for the first week of September 2026 (September 1–6). During the period, national passenger vehicle retail sales were 210,000 units, down 19% year on year and down 1% month on month; manufacturer wholesale was 207,000 units, down 21% year on year and up 13% month on month, with both retail and wholesale averaging 35,000 units per day. While the overall trend was weak, the NEV segment continued to see rising penetration, with retail penetration reaching 71.5% and wholesale penetration reaching 75.1%.
Retail Down 19% YoY, Cumulative Decline Still Over 20%
On the retail side, national passenger vehicle retail sales from September 1–6 were 210,000 units, down 19% year on year and down 1% month on month; cumulative retail sales since the start of the year were 11.926 million units, down 21% year on year. On a daily average basis, first-week daily retail sales were 35,000 units, down 19% year on year and down 1% month on month.
Wholesale showed a slight divergence. From September 1–6, manufacturer wholesale was 207,000 units, down 21% year on year but up 13% month on month, with daily average wholesale of 35,000 units; cumulative wholesale since the start of the year was 17.39 million units, down 5% year on year. On a cumulative basis, the 5% year-on-year decline on the wholesale side was significantly smaller than the 21% decline on the retail side, and this gap between the two measures was also present in the first-week data.
It should be noted that the first-week statistical period covered only six days and was at the beginning of the month. Single-week data are heavily affected by production scheduling and the distribution of working days, so the trend still needs to be observed in conjunction with subsequent weekly data.
NEV Decline Narrows, Wholesale Penetration Rises to 75.1%
The NEV market was a relatively stable part of the first-week data. On the retail side, NEV passenger vehicle retail sales from September 1–6 were 150,000 units, down 3% year on year and up 15% month on month; cumulative retail sales since the start of the year were 6.824 million units, down 12% year on year. On the wholesale side, NEV passenger vehicle wholesale was 156,000 units, up 2% year on year and up 20% month on month; cumulative wholesale since the start of the year was 9.934 million units, up 9% year on year, achieving positive growth on a cumulative basis.
Compared with the overall market, the year-on-year decline in NEV retail (3%) was smaller than that of passenger vehicles overall (19%), while wholesale achieved positive growth of 2%, compared with a 21% year-on-year decline in overall wholesale. In terms of penetration, retail penetration was 71.5% and wholesale penetration was 75.1%, with the wholesale measure about 3.6 percentage points higher than retail.

Fuel Vehicles Drag Down Wholesale; Pure-Fuel Light Vehicle Production Down 47% YoY
First-week manufacturer sales were generally sluggish. The CPCA explicitly noted that the sharp decline in fuel vehicle retail dragged down first-week fuel vehicle manufacturer wholesale by 53%. This decline was significantly larger than the 21% year-on-year decline in overall passenger vehicle wholesale, indicating that the structural divergence on the wholesale side mainly came from fuel vehicles.
The production side also showed structural differences. From September 1–6, production of pure-fuel light vehicles was 101,000 units, down 47% year on year and up 86% month on month; production of hybrid and plug-in hybrid models was 85,000 units, down 11% year on year and up 35% month on month. Both production lines rebounded noticeably month on month, but moved in opposite directions year on year, indicating that changes in the year-on-year base and product mix are simultaneously affecting the supply side.
From the data relationship, fuel vehicles were under pressure in both retail and wholesale, while NEVs maintained positive growth on the wholesale side—directly producing the first-week market feature of "declining total volume, upward structural shift."
"Golden September and Silver October" Footfall Expected to Recover, but High Base May Limit Gains
Regarding the subsequent trend, the CPCA believes that September enters the traditional "Golden September and Silver October" peak season, and terminal footfall is expected to recover, but the high base in the same period last year may suppress the extent of this month's rebound.
Based on the disclosed data, this judgment corresponds to two observable variables: first, month-on-month measures have already shown signs of improvement—wholesale up 13% month on month, NEV retail up 15%, NEV wholesale up 20%, and on the production side pure-fuel light vehicles and hybrid/plug-in hybrid vehicles up 86% and 35% month on month, respectively; second, year-on-year measures remain constrained by the high base, with retail and wholesale down 19% and 21% year on year, respectively, and fuel vehicle wholesale down as much as 53%.
For industry practitioners, the first-week data reflect more the structural characteristics of the peak-season startup phase than the full-month trend. NEV penetration standing above 70% and cumulative NEV wholesale turning positive year on year contrast with the deep decline in fuel vehicle wholesale; under expectations of recovering footfall during "Golden September and Silver October," how much the high year-on-year base can offset month-on-month improvement will be a key observation point in subsequent weekly data for September.